
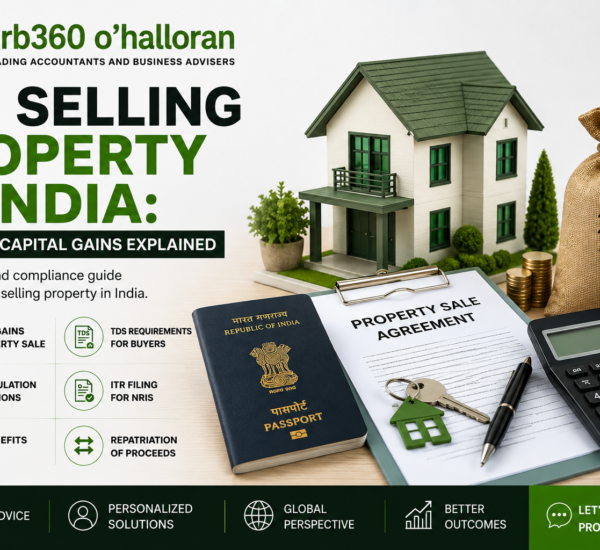
NRI Selling Property in India: Tax, TDS & Capital Gains Explained
Selling an Indian property while living overseas can create several tax and compliance questions. For an NRI selling property in India, the transaction may involve capital gains, TDS, Indian tax-return requirements, DTAA considerations and, in some cases, foreign-exchange and repatriation requirements.
The tax outcome depends on factors such as your residential status, when and how the property was acquired, the sale value, eligible costs, the nature of the gain, your country of tax residence and the rules applicable to the transaction.
NRI Selling Property in India
An NRI selling property in India may have Indian tax, TDS, capital-gains and reporting obligations. The exact requirements depend on the NRI’s residential status, type and location of the property, acquisition and sale details, applicable Indian tax provisions and whether a DTAA with the NRI’s country of tax residence affects the tax treatment.
For an NRI selling property in India, the key areas to review include:
- Capital gains: Determine whether the sale creates a short-term or long-term capital gain under the applicable rules.
- TDS: The buyer may have withholding obligations when purchasing property from a non-resident.
- Tax return: The NRI may need to report the transaction and capital gain through an Indian income-tax return.
- DTAA: A relevant tax treaty may affect taxation or relief from double taxation.
- Documentation: Purchase records, improvement costs, sale documents and TDS records can be important.
- Repatriation: Moving sale proceeds outside India may involve separate banking, foreign-exchange and documentation requirements.
The most important point: an NRI should ideally review the tax position before completing the property sale rather than waiting until after the transaction.
Quick Answer: What Tax Does an NRI Pay When Selling Property in India?
When an NRI selling property in India completes a property transaction, the sale can create Indian capital-gains tax implications.
The tax treatment depends on factors such as:
- When the property was acquired
- When it is sold
- The type of property
- The sale consideration
- Cost of acquisition
- Eligible transfer-related expenses
- Applicable capital-gains provisions
- The NRI’s residential status
- Whether a DTAA applies
The Income Tax Department’s current return documentation includes reporting requirements for capital gains from the sale of land or buildings.
TDS is a separate consideration. The buyer’s withholding obligations can apply when purchasing immovable property from a non-resident, and the applicable provisions depend on the tax law applicable to the transaction.
Who Is an NRI for Indian Tax Purposes?
Before calculating tax on a property sale, the individual’s residential status should be established.
Being an Indian citizen living overseas does not, by itself, determine your tax status.
The Income Tax Department determines residential status using statutory conditions, including the individual’s period of stay in India and specific provisions applicable to Indian citizens and persons of Indian origin.
This matters because residential status can affect how income is taxed in India.
Why Does Residential Status Matter?
For an NRI selling property in India, establishing residential status is one of the first steps in determining the wider tax position.
The basic review should consider:
Residential status → property details → capital gain → TDS → return filing → DTAA
Is Property Sold by an NRI Taxable in India?
Generally, the sale of immovable property located in India can create Indian tax implications even when the owner lives overseas.
The fact that the seller lives in New Zealand, Australia, the UK, the USA, Canada, Singapore or another country does not automatically remove Indian tax considerations on Indian property.
For an NRI selling property in India, the property and transaction need to be examined under the applicable Indian tax rules.
How Is Capital Gain Calculated on an NRI Property Sale?
The basic calculation can be represented as:
Sale consideration
Less:
- Eligible cost of acquisition
- Eligible cost of improvement
- Eligible transfer-related expenses
= Capital gain
The applicable deductions depend on the nature of the transaction and the law applicable for the relevant period.
For an NRI selling property in India, useful records may include:
- Original purchase agreement
- Sale deed
- Purchase consideration records
- Stamp-duty records
- Registration costs
- Improvement invoices
- Brokerage records
- Legal expenses
- Previous valuation documents
- TDS certificates
Keeping these documents is particularly important when the property was purchased many years ago.
Short-Term vs Long-Term Capital Gains on Indian Property
The holding period can affect how an Indian property transaction is classified for capital-gains purposes.
For immovable property, the Income Tax Department has stated that the relevant holding-period threshold is 24 months for determining whether the property is long-term or short-term under the applicable rules.
Therefore, an NRI selling property in India should establish:
Date of acquisition → holding period → date of transfer → applicable capital-gains treatment
The applicable tax rate and calculation should then be determined under the law relevant to the transaction.
NRI Property Sale and TDS: What Does the Buyer Need to Know?
TDS is one of the most important considerations when an NRI selling property in India enters into a transaction.
TDS treatment for a non-resident seller is different from the standard process that may apply to a resident seller.
The applicable rules should be reviewed based on:
- The seller’s residential status
- Property type
- Sale consideration
- Applicable TDS provisions
- Date of payment or credit
- Applicable tax year
- Required forms and documentation
For transactions from 1 April 2026, the Income Tax Act, 2025 has reorganised the TDS framework, including provisions covering certain transfers of immovable property.
Does the Buyer Deduct TDS When Buying Property From an NRI?
The buyer may have withholding obligations when purchasing immovable property from a non-resident.
The applicable provisions should be confirmed based on the transaction date, seller’s residential status and nature of the property transaction.
This is why an NRI selling property in India should clarify the withholding position before completing the sale.
What Happens if Too Much TDS Is Deducted?
An NRI may sometimes have more tax withheld than their final tax liability.
If the amount withheld exceeds the final tax liability, the excess may potentially be claimed through the applicable Indian tax-return process, subject to the relevant rules.
An NRI selling property in India should therefore retain:
- TDS certificates
- Sale documentation
- PAN details
- Purchase records
- Capital-gains calculation
- Tax payment records
The final tax liability should be calculated rather than assuming that the amount withheld represents the final tax.
Can an NRI Claim a TDS Refund After Selling Property?
Potentially, yes.
If the TDS deducted is higher than the final tax liability, the excess may be refundable through the applicable income-tax return process.
Before claiming a refund, the NRI should ensure that:
- The property sale has been correctly reported.
- The capital gain has been correctly calculated.
- TDS has been correctly reflected.
- The appropriate Indian return has been filed where required.
- Any applicable DTAA position has been considered.
Does an NRI Need to File an Indian Tax Return After Selling Property?
An NRI may need to file an Indian income-tax return when the applicable filing conditions are met.
The appropriate return depends on the individual’s complete income profile and the nature of income earned during the relevant financial year.
Capital gains are among the types of income that may need to be reported in the applicable return.
TDS deducted does not automatically mean an NRI does not need to file a tax return.
For an NRI selling property in India, the complete income position should be reviewed before deciding whether a return is required.
Can DTAA Reduce Tax on an NRI Property Sale?
A Double Taxation Avoidance Agreement (DTAA) may become relevant if the NRI is tax resident in another country.
However, a DTAA does not automatically make an Indian property sale tax-free.
The relevant treaty should be examined based on:
- Country of tax residence
- Type of income
- Location of the property
- Applicable treaty article
- Indian domestic law
- Foreign-country tax treatment
- Documentation requirements
For example, an NRI living in New Zealand and selling property in India may need to consider both Indian tax rules and the India-New Zealand tax position.
For an NRI selling property in India, treaty analysis should be based on the specific transaction rather than assuming that every NRI receives identical treatment.
Tax Residency Certificate and DTAA Claims
If treaty relief is being considered, supporting documentation can become important.
Depending on the circumstances, an NRI may need documentation such as:
- Tax Residency Certificate
- PAN
- Tax identification information
- Income details
- TDS certificates
- Property records
- Other prescribed information
The exact documentation should be confirmed for the relevant country and tax year.
NRI Selling Inherited Property in India
Inherited property can create additional questions.
For example:
- When did the original owner acquire the property?
- What was the original cost?
- When was the property inherited?
- What is the relevant acquisition value?
- Has the property been improved?
- When is the NRI selling it?
- What supporting documents are available?
An NRI selling property in India that was inherited should avoid assuming that the purchase price is simply the amount paid by the current owner.
The property’s acquisition history should be reviewed under the applicable capital-gains rules.
NRI Selling Property Purchased Many Years Ago
Older property transactions can be more complicated because documentation may be incomplete.
You may need to locate:
- Original sale deed
- Purchase agreement
- Registration records
- Historical valuation information
- Improvement bills
- Property-tax records
- Loan documents
- Sale documentation
For an NRI selling property in India, reconstructing the property’s acquisition and improvement history can be important when calculating the taxable gain.
NRI Property Sale and Reinvestment
An NRI may want to explore whether the capital gain can qualify for an available exemption or relief through reinvestment.
The availability of relief depends on the specific asset, transaction, reinvestment and statutory conditions.
If you are considering reinvesting the proceeds, it is advisable to understand the relevant conditions before completing the sale or reinvestment.
For an NRI selling property in India, professional review before the transaction can help identify whether any potential relief should be investigated.
Repatriating Property Sale Proceeds Outside India
Selling the property and moving the proceeds overseas are separate considerations.
An NRI may need to consider:
- Indian tax compliance
- TDS
- Bank documentation
- Source of funds
- FEMA requirements
- Repatriation rules
- Applicable banking procedures
- Foreign-country tax obligations
The ability to remit funds should therefore be reviewed separately from the capital-gains calculation.
An NRI selling property in India who intends to transfer substantial proceeds overseas should review the applicable requirements before making the transfer.
Common Mistakes NRIs Make When Selling Indian Property
1. Treating an NRI Property Sale Like a Resident Sale
The TDS and compliance process can differ when the seller is a non-resident.
2. Waiting Until After the Sale to Calculate Tax
This can make it harder to plan the transaction and organise the necessary documentation.
3. Ignoring DTAA
The NRI’s country of tax residence may affect the overall tax position.
4. Losing Original Property Documents
Purchase and improvement records can be important for determining the capital gain.
5. Assuming TDS Is the Final Tax
TDS is a withholding mechanism. The final tax liability needs to be determined under the applicable rules.
6. Ignoring Repatriation Requirements
Moving sale proceeds overseas may involve separate banking and foreign-exchange requirements.
7. Assuming an Inherited Property Has No Tax
Inherited property can still generate capital-gains implications when sold.
8. Not Reviewing the Transaction Before Signing
Tax planning is generally more useful before the transaction than after it.
NRI Property Sale: Pre-Sale Tax Checklist
Before an NRI selling property in India completes a transaction, the following areas should be reviewed.
Residential Status
- What is my Indian tax residential status?
- Which country am I tax resident in?
Property
- When was the property acquired?
- Was it purchased or inherited?
- What was the original cost?
- What improvements were made?
- What is the expected sale price?
Tax
- Will the transaction create capital gains?
- Is the gain short-term or long-term?
- What deductions or reliefs may apply?
- What tax rate applies?
TDS
- Is the buyer required to deduct TDS?
- What provisions apply to a non-resident seller?
- Is the amount being withheld appropriate?
DTAA
- Does India have a DTAA with my country of tax residence?
- Could treaty provisions affect the tax position?
- Do I have the necessary documentation?
Repatriation
- Can the sale proceeds be remitted overseas?
- What bank documentation is required?
- Are FEMA considerations relevant?
Why Pre-Sale Tax Planning Matters for NRIs
For an NRI selling property in India, tax planning should ideally happen before the sale agreement is finalised.
A pre-sale review can help identify:
- Expected capital gains
- Potential TDS
- Documentation gaps
- DTAA considerations
- Potential exemptions
- Reinvestment opportunities
- Return-filing requirements
- Repatriation considerations
This can give the seller a clearer picture of the potential financial and compliance implications before completing the transaction.
How DFK Orb360 O’Halloran Can Help With NRI Property Tax
Selling property in India while living overseas can involve more than calculating capital gains.
DFK Orb360 O’Halloran provides accounting, taxation, compliance, financial reporting and business advisory support.
Depending on your circumstances, a review may cover:
- Capital-gains considerations
- Indian tax compliance
- TDS review
- Tax-return requirements
- DTAA considerations
- Documentation
- Business and investment tax matters
- Cross-border accounting support
If you are an NRI selling property in India, getting professional advice before the transaction can help you understand the tax and compliance issues that may affect the sale.
Explore DFK Orb360 O’Halloran’s accounting and tax services →
Need Help Before Selling Your Indian Property?
Don’t wait until the property is sold.
If you are an NRI planning to sell property in India, DFK Orb360 O’Halloran can help you identify the key tax and compliance questions that should be reviewed before the transaction.
Tell us about your property, country of residence and planned sale, and our team can help identify the areas that require attention.
Speak with DFK Orb360 O’Halloran about your NRI tax requirements.
People Also Ask: NRI Selling Property in India
Does an NRI pay tax when selling property in India?
An NRI selling property in India can have Indian capital-gains tax implications. The actual tax treatment depends on the property, holding period, transaction details and applicable law.
What is the TDS rate when an NRI sells property in India?
The applicable withholding depends on the provisions governing payments to a non-resident and the nature of the transaction. The applicable provisions should be checked for the transaction date.
Does the buyer deduct TDS when buying property from an NRI?
The buyer may have withholding obligations when purchasing immovable property from a non-resident. The applicable rules should be confirmed based on the transaction and the law applicable at the time.
Does an NRI need to file a tax return after selling property?
An NRI may need to file an Indian tax return if the applicable filing conditions are met. Capital gains are among the types of income that may need to be reported through the applicable return.
Can an NRI claim a refund of excess TDS?
Potentially. If the amount withheld exceeds the final tax liability, the excess may be refundable through the applicable tax-return process, subject to the relevant rules.
Does DTAA apply when an NRI sells Indian property?
A DTAA may be relevant where the NRI is tax resident in another country. The applicable treaty article and domestic tax rules need to be examined for the specific property sale.
Can an NRI sell inherited property in India?
An NRI can potentially sell inherited Indian property, but the transaction can involve capital-gains and documentation considerations. The property’s acquisition history and applicable tax rules should be reviewed.
Can an NRI repatriate property sale proceeds?
Repatriation can involve separate banking, foreign-exchange and documentation requirements. The applicable rules should be reviewed before transferring substantial sale proceeds overseas.
Why Getting Professional Advice Matters When Selling Property in India
An NRI selling property in India can face multiple tax and compliance considerations. The transaction may involve capital gains, TDS, Indian tax-return requirements, DTAA considerations and potentially foreign-exchange and repatriation requirements.
The outcome can vary depending on factors such as residential status, when and how the property was acquired, the sale value, improvement costs, country of tax residence and the rules applicable on the date of sale.
This is why an NRI property sale should ideally be reviewed before the transaction is completed. Reviewing the expected capital gain, applicable TDS, available documentation and potential treaty considerations in advance can help the seller understand the likely tax position and avoid compliance issues later.
DFK Orb360 O’Halloran provides accounting, taxation, compliance, financial reporting and business advisory support. For clients with cross-border interests, we can help identify the key accounting and tax matters that may need to be considered based on the individual’s circumstances.
Indian tax rules and withholding requirements can change, particularly with the transition to the Income Tax Act, 2025. DTAA treatment can also differ depending on the NRI’s country of tax residence. Current government guidance and the specific facts of the transaction should therefore be considered before making a tax decision.
If you are an NRI selling property in India, getting the tax position reviewed before signing or completing the transaction can give you a clearer understanding of potential capital gains, TDS and reporting obligations.
Looking to sell property in India as an NRI? Speak with DFK Orb360 O’Halloran to discuss the tax and compliance considerations relevant to your situation.
This article provides general educational information and is not personalised tax, legal or financial advice. The applicable treatment should be confirmed based on the transaction date, residential status, property details and relevant Indian and treaty provisions.
Official Sources for NRI Property Tax Information
For current information, readers should refer to official government sources:
Final Takeaway: Selling Indian Property as an NRI
If you are an NRI selling property in India, your tax position depends on more than the sale price.
Residential status, acquisition history, capital gains, TDS, DTAA, tax-return requirements and repatriation considerations may all need to be reviewed.
The earlier these issues are assessed, the easier it can be to identify potential tax liabilities, documentation requirements and compliance obligations.
Speak with DFK Orb360 O’Halloran about your NRI property sale →

 09 377 4238
 Level 2, 6 Kingdon Street, Newmarket, Auckland
 help@orb360.co.nz