GST filing frequency NZ determines how often your business must prepare and submit Goods and Services Tax (GST) returns to Inland Revenue (IRD). Choosing the right frequency can help you manage cash flow, keep your records up to date and avoid the pressure of preparing several months of transactions at once.
GST Filing Frequency in New Zealand
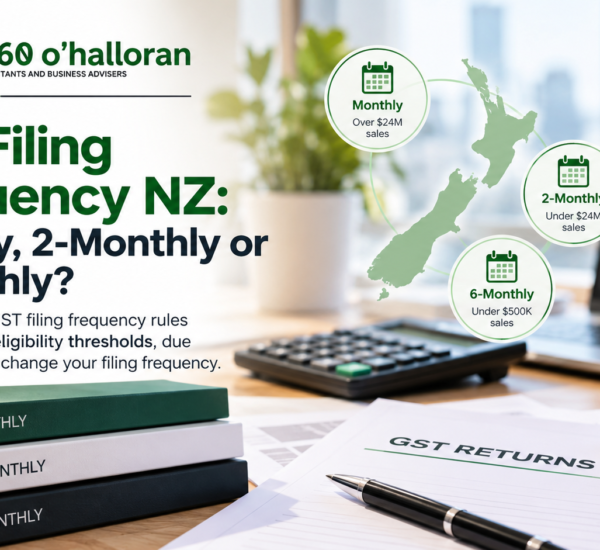
New Zealand businesses can generally choose monthly, two-monthly or six-monthly GST filing, depending on their circumstances and turnover. Businesses with sales exceeding NZ$24 million in any 12-month period must generally file monthly. Businesses with sales under NZ$24 million can use two-monthly filing, while businesses with sales under NZ$500,000 may qualify for six-monthly filing. Certain non-resident businesses supplying only specified services or goods must file quarterly.
GST filing periods must align with the business’s income tax balance date where required. Eligible businesses can request a change through myIR, but should continue using their existing filing frequency until IRD confirms the effective date.
Official source: IRD guidance on changing GST filing frequency.
For small businesses, sole traders and growing companies, the decision is not simply about filing fewer returns. It is also about how frequently you want to review your GST position, how many transactions you process, whether you regularly receive GST refunds and how well your accounting systems support regular reporting.
In this guide, DFK Orb360 O’Halloran explains the GST filing frequency options in New Zealand, the turnover thresholds, how filing periods align with your balance date, how to change your frequency and the common mistakes businesses should avoid.
What Is GST Filing Frequency?
GST filing frequency is the interval at which a GST-registered business submits its GST return to Inland Revenue. IRD also refers to the period covered by a GST return as the taxable period.
A GST return reports the relevant GST collected on taxable sales and the GST claimed on eligible business purchases and expenses. Depending on the business’s GST position, the return may result in GST payable to IRD or a refund.
Your filing frequency determines how often you must complete this reporting. It does not, by itself, determine how you account for GST on sales and purchases. That is governed by your separate GST accounting basis.
What Are the GST Filing Frequency Options in NZ?
IRD provides three standard filing frequency options for most New Zealand GST-registered businesses: monthly, two-monthly and six-monthly. A specific quarterly requirement also applies to certain non-resident businesses.
| Filing frequency | General eligibility | When it may suit you |
|---|---|---|
| Monthly | Available to businesses generally. Generally compulsory when sales exceed NZ$24 million in any 12-month period. | Businesses with high turnover, frequent GST refunds or a preference for regular reporting. |
| Two-monthly | Available to businesses with sales under NZ$24 million in any 12-month period. | Businesses that want regular reporting without filing every month. |
| Six-monthly | Available to businesses with sales under NZ$500,000 in any 12-month period. | Smaller businesses with relatively few transactions that can maintain accurate records over a longer period. |
| Quarterly | Required for certain non-resident businesses that only supply specified remote services, low-value imported goods or listed services. | Relevant to eligible non-resident suppliers under the applicable GST rules. |
Read the full rules on the IRD page explaining GST accounting basis and filing frequency.
1. Monthly GST Filing in New Zealand
Monthly filing means preparing and submitting a GST return for each monthly taxable period. Any GST payment due must also be made by the applicable deadline.
Who must file monthly GST returns?
IRD states that businesses must generally file monthly when their sales exceed NZ$24 million in any 12-month period. For a GST group, the threshold applies to the group as a whole.
Businesses below this threshold can also choose monthly filing if it is suitable for their circumstances. Monthly returns may be particularly useful for businesses that regularly receive GST refunds.
Potential advantages of monthly filing
- More frequent visibility: You review your GST position more regularly.
- Smaller reporting periods: You deal with one month’s transactions at a time.
- Refund management: Eligible businesses may receive refunds sooner than they would under less frequent filing, subject to IRD processing.
- Regular financial discipline: Monthly reporting can encourage timely reconciliation of sales, expenses and GST records.
What should you consider?
Monthly filing requires more frequent preparation, reconciliation and submission. If your bookkeeping is disorganised or your accounting systems are not updated regularly, the extra reporting cycle can create administrative pressure.
Before choosing monthly filing voluntarily, consider whether your business can consistently maintain accurate records and meet every return deadline.
2. Two-Monthly GST Filing in New Zealand
Two-monthly filing means submitting a GST return for each two-month taxable period. It is a common option for businesses that want regular reporting without the administrative demands of monthly returns.
Who can file two-monthly GST returns?
According to IRD, businesses with sales under NZ$24 million in any 12-month period can generally choose two-monthly filing. The threshold applies to the combined group where the business is part of a GST group.
Why choose two-monthly filing?
- It creates a regular routine for bookkeeping and GST reconciliation.
- It gives business owners more frequent visibility than six-monthly filing.
- It reduces the number of returns compared with monthly filing.
- It can help identify missing invoices, incorrect GST treatment or cash-flow issues before they accumulate over a longer period.
Example: A growing service business
Imagine a New Zealand consultancy that processes regular client invoices and supplier expenses throughout the year. The business has sales below NZ$24 million and is eligible for two-monthly filing.
By reviewing its GST records every two months, the owner can check that sales have been recorded, eligible expenses are supported by appropriate records and the GST return reflects the relevant taxable period. This creates a manageable reporting routine without requiring a return every month.
This is an illustrative example, not a determination of the filing frequency suitable for any particular business.
3. Six-Monthly GST Filing in New Zealand
Six-monthly filing allows eligible businesses to submit two GST returns per year. It may appeal to smaller businesses with relatively few transactions and straightforward record-keeping.
Who can file six-monthly GST returns?
IRD states that a business may use six-monthly filing if its sales are under NZ$500,000 in any 12-month period. For a GST group, the threshold applies to the group as a whole.
Benefits of six-monthly filing
- Fewer GST returns to prepare and submit each year.
- Less frequent filing administration.
- Potential suitability for businesses with low transaction volumes.
What are the risks of filing every six months?
Filing less frequently does not remove the need to maintain accurate records throughout the year. Six months of sales and purchases can create a substantial reconciliation task if the business leaves its bookkeeping until the return is due.
Other considerations include:
- Cash-flow planning: A GST payment can be significant when it relates to six months of activity.
- Record quality: Missing receipts and supplier invoices may be harder to resolve after several months.
- Less frequent oversight: Errors may remain undetected for longer.
- Business growth: Increasing sales may affect whether you remain eligible for six-monthly filing.
Six-monthly filing can reduce the number of returns, but it should not mean postponing bookkeeping. Regular reconciliations can help you understand your GST position before the return is due.
4. When Is Quarterly GST Filing Required?
Quarterly GST filing is not one of the three standard filing options available to most domestic businesses. IRD specifies quarterly filing for certain non-resident businesses that only supply:
- Remote services.
- Low-value imported goods.
- Listed services.
The applicable rule depends on the nature of the non-resident business and the supplies it makes. If a business begins supplying other types of goods or services, it may need to change to monthly, two-monthly or six-monthly filing, depending on its circumstances.
Non-resident businesses should check the relevant guidance before assuming that the standard domestic filing options apply.
Official guidance: IRD information on supplying remote services into New Zealand.
How Do You Choose the Right GST Filing Frequency?
The right choice depends on eligibility, transaction volume, accounting capacity and how frequently you need visibility into your GST position. The least frequent option is not automatically the best option for every eligible business.
Consider your turnover
Start by checking your sales over the relevant 12-month period. Monitor turnover as your business grows, rather than relying only on the figures recorded when you first registered for GST.
If your sales exceed NZ$24 million in a 12-month period, monthly filing is generally required. If sales are under NZ$500,000, six-monthly filing may be available. Other eligible businesses below the NZ$24 million threshold can generally use two-monthly filing.
Where turnover is close to a threshold, confirm the applicable rule with IRD or a qualified tax adviser. Do not assume that an exact threshold amount is treated the same as an amount above or below it.
Consider how often you receive GST refunds
If your business regularly incurs substantial GST-bearing expenses relative to its taxable sales, you may often have a refund position. Monthly filing may help eligible businesses submit refund claims more frequently, although the timing of any refund depends on IRD processing and other relevant factors.
Consider your transaction volume
A business with a small number of transactions may find six-monthly filing manageable. A business with many invoices, expenses, inventory transactions or complex operations may benefit from more frequent reconciliation and reporting.
Consider cash flow
GST collected from customers is not the same as money available to spend on business operations. Set aside funds for GST and use reliable records to estimate what may be payable.
With less frequent filing, a business may accumulate a larger GST payment before its return deadline. Choose a process that helps you manage the liability, not simply a frequency that minimises administration.
Consider your accounting systems
Cloud accounting software, regular bank reconciliation, organised expense records and a consistent invoicing process can make more frequent filing easier. If your records are currently incomplete, improving the process is more valuable than relying on a long filing period to delay the work.
GST Filing Frequency vs GST Accounting Basis: What Is the Difference?
These terms are related, but they refer to two different decisions.
| Term | What it determines | Examples |
|---|---|---|
| Filing frequency | How often you submit GST returns. | Monthly, two-monthly or six-monthly. |
| Accounting basis | When sales and purchases are included in your GST calculations. | Payments basis, invoice basis or hybrid basis. |
Under the payments basis, GST is generally accounted for when payments are made or received, subject to the applicable rules. Under the invoice basis, transactions are generally accounted for based on invoices and relevant taxable supply information, even if payment has not yet been made. The hybrid basis combines elements of the invoice and payments approaches.
Changing your filing frequency does not automatically change your accounting basis. If you want to change both, check the eligibility requirements and change process for each separately.
Read more in IRD’s guide to choosing a GST accounting basis and filing frequency.
How Does Your Income Tax Balance Date Affect GST Filing?
Your income tax balance date is the end of your financial year. For most New Zealand businesses, this is 31 March.
IRD says your GST filing frequency must align with your income tax balance date. This matters particularly for businesses using two-monthly or six-monthly periods.
Example: A business with a 31 March balance date
For a business with a 31 March balance date, the standard two-monthly periods align with the following month-end dates:
- May
- July
- September
- November
- January
- March
For a business using six-monthly filing with a 31 March balance date, the periods generally end on 30 September and 31 March.
Your actual taxable periods and obligations should be checked against your myIR account and any arrangements approved by IRD. Do not change your reporting periods based only on a general example.
When Must You Change Your GST Filing Frequency?
Your eligibility can change as your business grows or your sales fluctuate. IRD advises businesses to check whether they remain eligible when sales in any 12-month period change.
For example, a business that previously qualified for six-monthly filing may need to review its frequency if sales increase to NZ$500,000 or more. A business approaching the NZ$24 million threshold should also monitor turnover and confirm whether monthly filing is required.
GST groups need to consider the relevant group’s combined sales when applying the thresholds.
How to Change Your GST Filing Frequency in myIR
If you are eligible for a different filing frequency, IRD provides an online process through myIR.
- Log in to myIR. Access your Inland Revenue account using your usual login details.
- Open your GST account. Locate the relevant GST account.
- Select “More…”. Use the account menu to find the available account actions.
- Select “Update GST account details”.
- Choose the filing frequency. Select the option you want to change to, subject to eligibility.
- Wait for IRD confirmation. IRD states that it will contact you within 15 working days to tell you the date the change comes into effect.
Do not start using the new frequency until IRD confirms the effective date. Continue to meet the filing and payment requirements that apply to your current arrangement in the meantime.
For the official instructions, visit IRD’s step-by-step guide to changing GST filing frequency.
When Are GST Returns and Payments Due in NZ?
For most GST taxable periods, the return and any payment due must be filed and paid by the 28th day of the month following the end of the period.
IRD identifies two important exceptions:
- Period ending 31 March: The GST return and payment are generally due by 7 May.
- Period ending 30 November: The GST return and payment are generally due by 15 January of the following year.
If a due date falls on a weekend or public holiday, the applicable due-date rules should be checked with IRD. Always verify the date shown for your return in myIR, especially where a special arrangement or other circumstance applies.
See the official IRD guidance on filing GST returns, payments and refunds.
Do You Still Need to File a GST Return if There Was No Activity?
Yes. IRD states that a GST return is required for every taxable period, including periods when the return is a nil return.
If your business had no relevant activity during a taxable period, check how to complete the return correctly rather than assuming that no return is needed. A nil return is still part of your GST filing obligations when required.
Common GST Filing Frequency Mistakes to Avoid
1. Choosing a frequency based only on convenience
The easiest option administratively is not always the option you are eligible to use. Check your turnover, business structure and any special rules before changing frequency.
2. Forgetting to monitor turnover
Eligibility can change as sales rise or fall. Review the relevant 12-month period and act promptly if your circumstances mean you must change frequency.
3. Confusing filing frequency with accounting basis
Monthly, two-monthly and six-monthly describe how often you file. Payments, invoice and hybrid describe how you account for GST transactions. They are separate choices.
4. Changing your frequency before IRD confirms it
Submitting a change request does not mean you should immediately begin filing under the new frequency. Wait for confirmation of the effective date and follow the existing requirements until then.
5. Leaving bookkeeping until the GST return is due
Infrequent filing can mean a larger amount of work at the end of the period. Reconcile bank transactions, keep invoices organised and review GST coding throughout the year.
6. Missing a return because there is no GST to pay
A nil GST position does not automatically remove the obligation to file. Check the relevant taxable period and submit the return required by IRD.
7. Overlooking the balance-date alignment
Filing periods may need to align with your income tax balance date. Review your taxable periods when registering, changing frequency or updating your accounting arrangements.
How DFK Orb360 O’Halloran Can Help With GST Compliance
Choosing and maintaining the right GST filing frequency is part of keeping your business’s tax administration organised. A consistent process can help you identify potential issues earlier, plan for GST payments and keep your financial records in better shape.
DFK Orb360 O’Halloran works with businesses on accounting and tax matters. Depending on your needs and the scope agreed, professional support may include reviewing GST reporting processes, helping you understand your filing obligations, improving bookkeeping routines and discussing how GST fits into wider business planning.
If you are unsure whether your current filing frequency is appropriate, review your turnover, transaction volume, refund position and balance date before making a change.
Need Help With Your GST Filing Frequency?
Speak with DFK Orb360 O’Halloran about your GST reporting requirements and the next steps for your business.
Request Your Free First Consultation
The initial consultation is subject to confirmation of scope and availability. Any further services and fees will be discussed before proceeding.
Frequently Asked Questions About GST Filing Frequency NZ
What is the GST filing frequency in NZ?
GST filing frequency is how often a GST-registered business submits its returns to Inland Revenue. Most businesses choose between monthly, two-monthly and six-monthly filing, subject to eligibility. Certain non-resident businesses have a quarterly filing requirement.
What is the turnover limit for monthly GST filing in New Zealand?
IRD generally requires monthly GST filing when sales exceed NZ$24 million in any 12-month period. Businesses below that threshold may also choose monthly filing. GST groups apply the relevant threshold to the group as a whole.
Can a small business file GST every six months?
A business may be eligible for six-monthly filing if its sales are under NZ$500,000 in any 12-month period. It should also consider whether it can manage six months of transactions, reconciliation and potential GST payments effectively.
Is two-monthly GST filing compulsory?
No. Two-monthly filing is one of the available options for eligible businesses with sales under NZ$24 million in any 12-month period. Your circumstances and applicable IRD rules determine which filing frequency you can use.
Can I change my GST filing frequency online?
Yes. IRD allows eligible businesses to request a change through myIR. Open the GST account, select “More…”, choose “Update GST account details” and select the filing frequency you want. Wait for IRD to confirm when the change takes effect.
How long does IRD take to confirm a filing frequency change?
IRD states that it will contact you within 15 working days to let you know the effective date of the change. Continue to follow your current filing requirements until the change is confirmed and takes effect.
What is the GST return due date in New Zealand?
GST returns and payments are generally due on the 28th of the month after the taxable period ends. Exceptions include periods ending 31 March, generally due 7 May, and periods ending 30 November, generally due 15 January. Check myIR and IRD guidance for your applicable deadline.
Do I need to file a GST return if my business has no sales?
IRD requires a GST return for every taxable period, including a nil return when applicable. Check your GST obligations and submit the required return even if there is no GST to pay.
Does GST filing frequency affect my GST accounting basis?
No. Filing frequency determines how often you file returns. Your accounting basis—payments, invoice or hybrid—determines when relevant transactions are accounted for in your GST calculations. They are separate settings.
Does my GST filing frequency need to align with my financial year-end?
IRD says your GST filing frequency must align with your income tax balance date. Most New Zealand businesses have a 31 March balance date, but you should confirm your own balance date and taxable periods.
Can I file GST quarterly if my business is in New Zealand?
Quarterly filing is specifically required for certain non-resident businesses that only supply remote services, low-value imported goods or listed services. Most domestic businesses should check the standard monthly, two-monthly and six-monthly options that apply to them.
Where can I get help with GST filing frequency in New Zealand?
You can review Inland Revenue’s official GST guidance or contact DFK Orb360 O’Halloran to discuss your business’s GST reporting requirements. The appropriate advice will depend on your turnover, business structure, filing history and other relevant circumstances.
Final Thoughts: Choose a GST Filing Frequency That Fits Your Business
The right GST filing frequency NZ depends on your turnover, eligibility, transaction volume, cash flow and ability to keep accurate records. Monthly filing offers more frequent reporting, two-monthly filing balances regular oversight with fewer returns, and six-monthly filing may suit eligible smaller businesses with relatively few transactions.
Monitor turnover as your business changes, keep your GST records up to date, align your taxable periods with your balance date where required and wait for IRD confirmation before implementing a change.
For the most accurate information, refer to IRD’s guidance on GST filing frequency. If you need help applying the rules to your business, contact DFK Orb360 O’Halloran to discuss your requirements.
Disclaimer: This article provides general information about GST filing frequency in New Zealand and is not individual tax, accounting or legal advice. IRD rules and your circumstances determine your obligations. Verify current requirements with Inland Revenue or a qualified adviser before acting.
Talk to DFK Orb360 O’Halloran
Have a question about GST filing frequency or your business tax obligations? Send us an enquiry.

 09 377 4238
 Level 2, 6 Kingdon Street, Newmarket, Auckland
 help@orb360.co.nz