The start of a new year can bring fresh opportunities for New Zealand businesses, but it also comes with important tax responsibilities. January is a particularly significant month for businesses managing GST, provisional tax, PAYE and fringe benefit tax (FBT) obligations.
With several payment deadlines falling in the middle and latter part of January 2027, businesses need to do more than simply mark dates on a calendar. They need to make sure funds are available, records are up to date and tax payments have been correctly calculated.
This guide explains the key January 2027 Tax Payments NZ deadlines, what businesses should prepare and how to manage cash flow before tax obligations become overdue.
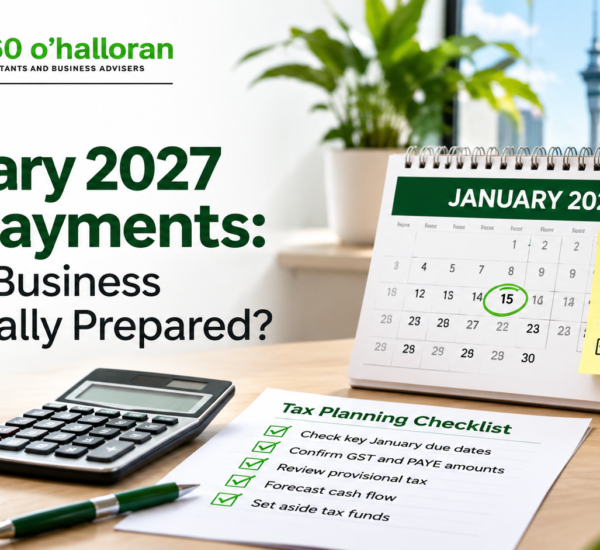
January 2027 includes important New Zealand tax deadlines, particularly 15 January for November GST returns and payments and certain provisional tax instalments. Employers also need to prepare for PAYE obligations, while businesses with quarterly FBT filing may have a return and payment due on 20 January. Good cash-flow forecasting, accurate records and early tax planning can help businesses meet these obligations without unnecessary financial pressure.
- 15 January 2027 is an important deadline for GST and provisional tax.
- PAYE payment obligations depend on employer size and payroll arrangements.
- Quarterly FBT returns and payments may be due on 20 January.
- Monthly GST filers should also check the 28 January deadline.
- Businesses should forecast tax payments and keep funds available ahead of deadlines.
January 2027 Tax Payments NZ: Key Dates to Remember
January has several important dates for businesses with a standard 31 March balance date. The following table provides an overview of the main obligations shown in Inland Revenue’s 2026–27 tax calendar.
| Date | Tax obligation | Who should check it? |
|---|---|---|
| 15 January 2027 | November GST return and payment | Businesses with a GST taxable period ending 30 November |
| 15 January 2027 | Provisional tax instalment | Eligible standard or estimation option taxpayers |
| 15 January 2027 | Ratio-option provisional tax instalment | Businesses using the ratio method |
| 20 January 2027 | PAYE and employer deductions | Employers, depending on payroll size and payment frequency |
| 20 January 2027 | Quarterly FBT return and payment | Businesses using quarterly FBT filing |
| 28 January 2027 | GST return and payment | Monthly GST filers with a December taxable period |
Important: These are general dates for businesses with a standard 31 March balance date. GST filing frequency, provisional tax method, payroll size and individual circumstances can change the applicable dates. Always confirm your obligations in myIR.
1. GST Returns and Payments: 15 January 2027
For businesses with a taxable period ending 30 November 2026, the GST return and payment are generally due on 15 January 2027. This is an important date to plan for, particularly after the Christmas and New Year trading period.
Before filing, businesses should:
- Reconcile sales and income for the taxable period.
- Check purchase invoices and eligible GST claims.
- Reconcile bank transactions and accounting records.
- Review GST collected and GST paid.
- Make sure sufficient funds are available for the payment.
Businesses that file GST monthly should also check the next deadline: 28 January 2027 for the taxable period ending 31 December 2026.
2. Provisional Tax: 15 January 2027
Provisional tax is paid during the income year to help businesses manage their income tax obligations in instalments rather than facing one large payment at the end of the year.
For taxpayers with a standard 31 March balance date, the second standard or estimation provisional tax instalment for the 2027 income year is generally due on 15 January 2027.
Businesses using the ratio option may also have their fourth instalment due on this date. The amount and payment schedule depend on the method being used and the business’s circumstances.
Which provisional tax method applies?
| Method | How it works |
|---|---|
| Standard method | Generally calculates provisional tax using a formula based on previous residual income tax. |
| Estimation method | Uses an estimate of the current year’s expected residual income tax. |
| Ratio method | Calculates provisional tax using a percentage of GST-taxable supplies. |
| Accounting Income Method (AIM) | Uses accounting software to calculate tax payments based on business income and expenses. |
If your business income has changed significantly, review whether your current provisional tax method and calculations remain appropriate. Do not change estimates without considering the potential consequences of underpaying.
3. PAYE and Employer Deductions: 15 and 20 January 2027
Businesses employing staff must ensure PAYE and other applicable employer deductions are paid to Inland Revenue according to their payment schedule.
For January 2027, the IRD calendar identifies employer deduction payment dates on 15 and 20 January. The applicable date depends on whether the employer is classified as a large or small-to-medium employer and on the relevant deduction period.
- 15 January: Large employers should check the payment obligation for deductions from the second half of December.
- 20 January: Employers should check the relevant PAYE and employer deduction payments for the applicable payroll period.
Employers should reconcile payroll records, confirm deductions and check their myIR account before making payments. Payday filing obligations are separate and should also be completed within the applicable timeframe.
4. Fringe Benefit Tax (FBT): 20 January 2027
Businesses providing certain non-cash benefits to employees may have fringe benefit tax obligations. Examples can include private use of work vehicles, subsidised transport, or certain goods and services provided to employees.
For businesses using quarterly FBT filing, the return and payment for the quarter ending 31 December 2026 are generally due on 20 January 2027.
Before filing, review:
- Company vehicles and employee private-use arrangements.
- Employee benefits provided during the quarter.
- Records supporting FBT calculations.
- Any changes to employee benefit arrangements.
Not every business has an FBT obligation. The rules depend on the benefits provided and the business’s circumstances.
5. January GST Deadline: 28 January 2027
Businesses filing GST monthly should also prepare for the next payment date. The GST return and payment for the taxable period ending 31 December 2026 are due on 28 January 2027.
This is particularly important for businesses that continue trading through the holiday period. Make sure December sales, expenses, invoices and adjustments are recorded accurately before filing.
Why January Tax Payments Can Put Pressure on Business Cash Flow
January can be challenging because tax payments arrive shortly after a period when many businesses experience seasonal changes in revenue and expenses.
Some businesses may have reduced trading activity over the holiday period, while others may have higher costs due to seasonal staffing, supplier payments or inventory purchases.
Common cash-flow challenges include:
- Lower cash reserves: Holiday closures or slower customer payments can reduce available funds.
- Overdue customer invoices: Outstanding payments may leave businesses without enough working capital.
- Multiple tax obligations: GST, provisional tax and payroll-related payments can fall close together.
- Unplanned expenses: Supplier costs, wages and operating expenses can compete with tax payments.
- Inaccurate forecasting: Businesses that do not set aside tax funds may struggle when deadlines arrive.
7 Practical Ways to Prepare Your Business for January 2027 Tax Payments
1. Prepare a tax payment calendar
List every relevant GST, PAYE, provisional tax and FBT deadline. Include the amount expected, the account responsible and the date funds need to be available.
2. Forecast cash flow before the holiday period
Prepare a short-term cash-flow forecast covering December 2026, January 2027 and February 2027. Include expected customer receipts, wages, supplier payments, operating costs and tax obligations.
3. Set aside money for tax payments
Keep tax funds separate from money available for everyday business expenses. This can help reduce the risk of spending funds that are already committed to Inland Revenue.
4. Follow up outstanding invoices
Review overdue customer accounts and follow up outstanding invoices before the holiday period. Clear payment terms and timely reminders can help improve collections.
5. Reconcile your accounting records
Make sure sales, expenses, bank transactions, payroll and GST records are up to date. Accurate records help reduce filing errors and make it easier to calculate the correct amount payable.
6. Review provisional tax estimates
If business income or profitability has changed, review whether your provisional tax calculations remain suitable. Seek professional advice before changing your payment approach.
7. Speak to your accountant early
Do not wait until a payment deadline is approaching to discuss a potential cash-flow shortfall. An accountant can help review your obligations, identify planning opportunities and discuss appropriate next steps.
What Happens If Your Business Cannot Pay on Time?
If your business expects to have difficulty meeting an Inland Revenue payment deadline, take action early rather than ignoring the obligation.
Depending on your circumstances, you may be able to discuss a payment arrangement with Inland Revenue. Options and eligibility depend on the tax type and your individual situation.
Late payments can result in penalties and use-of-money interest. The amount depends on the relevant tax type, timing and applicable rules.
Practical steps include:
- Review the amount outstanding and the payment deadline.
- Check your myIR account for the relevant tax account information.
- Prepare a realistic cash-flow forecast.
- Contact Inland Revenue or your tax adviser promptly.
- Discuss whether a payment arrangement or another suitable option is available.
Is Your Business Financially Prepared for 2027?
Being financially prepared means more than having enough money to pay your tax bill. It means understanding upcoming obligations, maintaining accurate financial records and knowing how tax payments fit into your wider business cash flow.
Before January begins, consider whether your business can answer these questions:
- Do you know which tax payments are due in January?
- Have you estimated how much needs to be paid?
- Are your GST and payroll records up to date?
- Have you reviewed your provisional tax position?
- Do you have enough cash available after covering wages and suppliers?
- Have you discussed any expected payment difficulties with your accountant?
If you cannot confidently answer these questions, it may be time to review your business’s financial position before the new year gets underway.
How DFK Orb360 Can Support Your Business
Managing tax obligations while running a business can be demanding, especially when several payment deadlines fall close together. Having a clear financial plan can help business owners make informed decisions and prepare for upcoming obligations.
DFK Orb360 O’Halloran Chartered Accountants works with businesses on accounting, tax and business advisory matters. Our team can help you review your financial position, understand relevant tax obligations and plan for upcoming payment commitments.
Whether you are reviewing provisional tax, preparing GST returns or looking for better cash-flow visibility, professional advice can help you approach the new year with greater confidence.
Prepare Your Business for January 2027
Do not let tax deadlines catch your business off guard. Speak with DFK Orb360 O’Halloran Chartered Accountants about your accounting, tax and financial planning requirements.
Frequently Asked Questions
1. What tax payments are due in January 2027 in New Zealand?
Key January obligations include GST and provisional tax on 15 January, employer deductions and quarterly FBT on 20 January, and monthly GST on 28 January. The dates that apply depend on your business and filing arrangements.
2. When is GST due in January 2027?
For a taxable period ending 30 November 2026, GST returns and payments are generally due on 15 January 2027. Monthly GST filers with a period ending 31 December 2026 should check the 28 January deadline.
3. When is provisional tax due in January 2027?
For taxpayers with a standard 31 March balance date, the second standard or estimation instalment and the fourth ratio-option instalment are generally due on 15 January 2027.
4. Do all businesses need to pay provisional tax in January?
No. Provisional tax obligations depend on residual income tax, the business’s tax position and the payment method being used. Check your myIR account or speak with your tax adviser.
5. When is PAYE due in January 2027?
PAYE and employer deduction dates depend on employer size and the relevant payroll period. The IRD calendar identifies 15 and 20 January 2027 as important employer deduction payment dates.
6. When is FBT due in January 2027?
Businesses using quarterly FBT filing generally need to file and pay for the quarter ending 31 December 2026 by 20 January 2027.
7. What happens if a business misses a tax payment deadline?
Late payment may result in penalties and use-of-money interest. Businesses that expect difficulty paying should contact Inland Revenue early to discuss whether a payment arrangement is available.
8. How can a business prepare for January tax payments?
Businesses can prepare by reviewing their tax calendar, forecasting cash flow, setting aside funds, reconciling accounting records, following up overdue invoices and reviewing provisional tax calculations.
9. Can an accountant help with January tax planning?
Yes. An accountant can help review upcoming tax obligations, prepare financial forecasts, check accounting records and discuss suitable approaches to managing business cash flow.
10. Where can I check my business’s exact tax due dates?
You can check your tax accounts and payment obligations through myIR and refer to Inland Revenue’s official website. Your tax agent can also help confirm the dates that apply to your circumstances.
Understanding the Tax Challenges Facing New Zealand Businesses
Managing multiple tax obligations can create cash-flow pressure for businesses, particularly when GST, provisional tax and employer deductions fall close together. Having accurate financial records and a forward-looking payment plan helps business owners understand their commitments and make informed financial decisions.
Every business has different tax obligations depending on its structure, filing frequency, accounting period and financial position. Reviewing these factors before payment deadlines approach can help reduce avoidable compliance issues.
Final Thoughts on January 2027 Tax Payments NZ
January 2027 Tax Payments NZ should be part of every business’s year-end and new-year financial planning. With GST, provisional tax, PAYE and FBT obligations falling throughout the month, preparation is essential to avoid unnecessary pressure on working capital.
By reviewing payment dates early, maintaining accurate records and forecasting cash flow, businesses can approach January with a clearer understanding of their financial commitments.
Start planning now so your business can enter 2027 financially prepared.
Disclaimer: This article provides general information for New Zealand businesses and is not tax or legal advice. Tax due dates and obligations may vary according to balance date, GST filing frequency, provisional tax method, payroll size and individual circumstances. Confirm applicable dates and requirements with Inland Revenue or a qualified tax adviser before making payments.
People Also Ask: January 2027 Tax Payments NZ
1. What are the important January 2027 Tax Payments NZ deadlines?
The important January 2027 Tax Payments NZ deadlines include GST and provisional tax on 15 January, employer deductions and quarterly FBT on 20 January, and monthly GST on 28 January. Businesses should confirm their individual obligations through myIR.
2. How can businesses prepare for January 2027 Tax Payments NZ?
Businesses can prepare for January 2027 Tax Payments NZ by reviewing their tax calendar, reconciling accounting records, forecasting cash flow and setting aside sufficient funds for upcoming payments.
3. When is the January 2027 GST payment due in New Zealand?
GST for the taxable period ending 30 November 2026 is generally due on 15 January 2027. Monthly GST filers should also prepare for the 28 January 2027 deadline.
4. What provisional tax payments are due in January 2027?
For businesses with a standard 31 March balance date, certain standard, estimation and ratio-option provisional tax instalments are due on 15 January 2027. The applicable instalment depends on the tax method used.
5. How do January 2027 Tax Payments NZ affect business cash flow?
January 2027 Tax Payments NZ can affect working capital because businesses may need to meet GST, provisional tax, PAYE and other obligations while managing wages, supplier invoices and operating expenses.
6. What happens if a business cannot afford its January tax payments?
If a business cannot afford its January tax payments, it should review its financial position and contact Inland Revenue promptly. Depending on eligibility, a payment arrangement may be available.
7. How can an accountant help with January 2027 Tax Payments NZ?
An accountant can help businesses understand January 2027 Tax Payments NZ obligations, review provisional tax calculations, prepare GST returns and develop cash-flow forecasts for upcoming tax commitments.
8. Should businesses set aside money for January tax payments?
Yes. Businesses should plan for January tax payments throughout the year by maintaining a tax reserve and regularly reviewing expected GST, income tax and employer deduction obligations.
9. Where can I check New Zealand business tax deadlines for January 2027?
Businesses can check January 2027 Tax Payments NZ dates through the official Inland Revenue website and their myIR accounts. A tax adviser can also help confirm the deadlines relevant to their circumstances.
10. How can businesses improve their financial planning for 2027?
Businesses can improve financial planning for 2027 by preparing monthly cash-flow forecasts, reviewing expenses, monitoring outstanding invoices, planning for tax payments and seeking professional accounting advice.

 09 377 4238
 Level 2, 6 Kingdon Street, Newmarket, Auckland
 help@orb360.co.nz