
How an Accountant Can Help Prepare Your Finances for a Mortgage Application in NZ
Preparing for a mortgage application in New Zealand? Before approaching a lender or mortgage adviser, it can help to have your financial information organised, accurate and ready to provide.
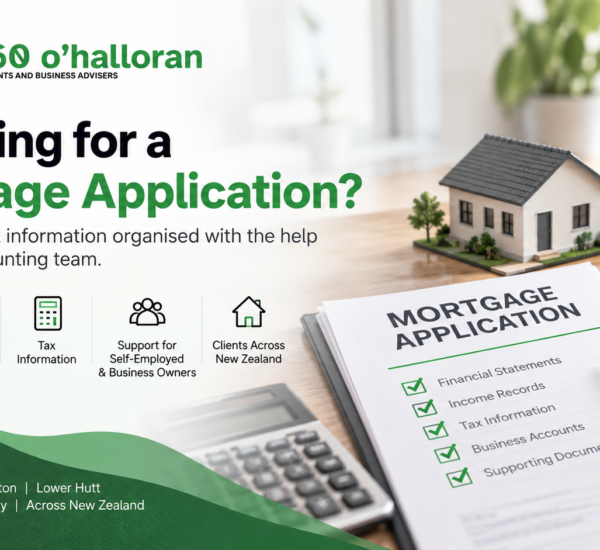
An accountant can help you prepare and review financial information such as financial statements, income records, tax information, business accounts and supporting documents that may be requested during a mortgage application.
At DFK Orb360 O’Halloran , we help business owners, self-employed professionals and other clients organise and understand their accounting and financial information when preparing for significant financial applications.
Quick Answer: Can an Accountant Help With a Mortgage Application?
Yes. An accountant can help organise and prepare financial information such as financial statements, income records, tax information, business accounts and supporting documents that may be required for a mortgage application.
However, accountants and mortgage advisers have different roles. A mortgage adviser provides advice about home loans and lending products, while an accountant can help prepare and explain accounting and financial information.
Why Your Financial Information Matters When Applying for a Mortgage
When you apply for a mortgage, a lender may request information about your income, expenses, assets, liabilities and overall financial position.
The exact documents required can vary depending on the lender, your circumstances and whether you are employed, self-employed or operating through a business.
For business owners and self-employed applicants, financial information can involve multiple records and income sources. Having these records organised can make it easier to respond when financial information is requested.
Your mortgage adviser or lender can tell you what information they require for your particular application. Your accountant can help you prepare relevant accounting information.
What Financial Information May Be Needed for a Mortgage Application?
Requirements vary between lenders and applicants. Depending on your circumstances, you may be asked for information such as:
- Personal income information
- Business income information
- Profit and loss statements
- Balance sheets
- Financial statements
- Tax returns and tax information
- Business bank records
- Details of existing debts and liabilities
- Evidence supporting income or business earnings
- Information about assets and business interests
- Other supporting documents requested by the lender
Always confirm the exact documentation requirements with your lender or mortgage adviser.
How an Accountant Can Help Prepare You for a Mortgage Application
1. Prepare Up-to-Date Financial Statements
If you operate a business, an accountant can help prepare or update financial statements that show the financial position of the business.
Depending on your circumstances, this may include a profit and loss statement and balance sheet.
Having current financial information available can make it easier to respond when a lender or mortgage adviser requests supporting documentation.
2. Review Your Income Information
Income can be more complex for business owners and self-employed individuals than for someone receiving a regular salary or wage.
An accountant can help identify and organise relevant income information from your accounting records and explain how different figures are reflected in your financial statements.
This does not mean an accountant determines how a lender will assess your income. The lender decides what income it recognises and what documentation it requires.
3. Organise Business Financial Records
If you operate a company, partnership or other business structure, you may have several financial records that need to be brought together.
An accountant can help organise relevant records and identify missing or outdated information before documents are provided for a mortgage application.
4. Check That Your Records Are Consistent
Inconsistencies between financial statements, tax information, accounting records and supporting documents can result in additional questions during an application.
Reviewing your records beforehand can help identify information that may require clarification or correction.
5. Help Explain Your Business Financial Position
Business owners may have income, expenses, drawings, shareholder salaries, company structures or other accounting considerations that are not immediately obvious from a single bank statement.
Your accountant can help explain the accounting information and provide relevant supporting documentation where appropriate.
6. Help You Understand What Your Financial Records Show
Preparing for a mortgage application can also be an opportunity to understand your current financial position.
Your accountant can help you understand figures such as business revenue, expenses, profitability, assets and liabilities based on your accounting records.
Mortgage Applications for Self-Employed People in NZ
Self-employed applicants may have additional financial information to organise because their income can come through a business rather than a standard salary or wage.
If you are self-employed, preparing your accounting records before beginning a mortgage application may help you respond more efficiently when financial documents are requested.
An accountant can assist with areas such as:
- Preparing current financial statements
- Reviewing business income and expenses
- Organising tax information
- Reviewing business and personal financial records
- Preparing supporting accounting information
- Identifying discrepancies that may need clarification
The lender or mortgage adviser will determine which documents are required and how the information is assessed.
What If You Are a Business Owner Applying for a Mortgage?
Business owners may need to provide information from both their business and personal financial position.
Your financial circumstances may involve:
- Company income
- Shareholder salary
- Drawings
- Business expenses
- Existing business debt
- Personal lending
- Property investments
- Multiple income sources
Because every applicant’s circumstances are different, the documents required will depend on the lender’s requirements and individual circumstances.
Accountant vs Mortgage Adviser: What’s the Difference?
Understanding the difference between these services is important when preparing for a mortgage application.
| Accountant | Mortgage Adviser |
|---|---|
| Helps prepare and explain accounting and financial information | Provides advice about home loans and lending products |
| Prepares financial statements and accounting records | Advises on lending options within their authorised scope |
| Helps organise tax and business financial information | Can work with lenders during the mortgage process |
| Provides accounting and tax services | Provides regulated financial advice where appropriately authorised |
According to the Financial Markets Authority (FMA) , mortgage advisers provide financial advice about home loans and lending products.
DFK Orb360 does not provide mortgage advice or recommend mortgage products or lenders. Our role is to help clients prepare and understand their accounting and financial information for purposes such as a mortgage application.
When Should You Speak to Your Accountant?
You do not necessarily need to wait until a lender or mortgage adviser requests your documents.
If you are considering applying for a mortgage, speaking with your accountant beforehand can help you understand whether your financial records are current and properly organised.
This can be particularly relevant if:
- You are self-employed
- You own a company
- You are a property investor
- Your income comes from multiple sources
- Your latest financial statements are outdated
- Your business has recently changed
- You are preparing for a significant lending application
Mortgage Application Preparation Checklist
Before beginning your application, consider whether you have access to the following:
- ☐ Current financial statements
- ☐ Recent income information
- ☐ Relevant tax records
- ☐ Business accounting records
- ☐ Bank statements or supporting records requested
- ☐ Details of existing debts and liabilities
- ☐ Information about relevant assets
- ☐ Supporting documents requested by your lender or mortgage adviser
Can an Accountant Improve My Chances of Getting a Mortgage?
An accountant cannot guarantee mortgage approval or determine whether a lender will approve an application.
What an accountant can do is help ensure that accounting and financial information is accurate, organised and appropriately prepared for the information requirements of your application.
The final lending decision belongs to the lender, based on its own lending criteria and assessment process.
Mortgage Application Accounting Support Across New Zealand
DFK Orb360 O’Halloran provides accounting, tax and business advisory services to clients across New Zealand.
Our team works with clients in Newmarket, Albany, Auckland, Wellington, Lower Hutt and other locations across New Zealand.
If you are a business owner, self-employed professional or property investor, our team can help you organise and understand your financial information when preparing for a mortgage application.
You can also explore our DFK Orb360 contact page to find our office locations and contact details.
Preparing for a Mortgage Application?
Before approaching a lender or mortgage adviser, make sure your financial records are up to date, accurate and organised.
Talk to DFK Orb360 about preparing your accounting and financial information for your mortgage application.
Whether you’re based in Auckland, Newmarket, Albany, Wellington, Lower Hutt or elsewhere in New Zealand, our team can help you understand and prepare your financial records.
People Also Ask
Can an accountant help with a mortgage application in New Zealand?
Yes. An accountant can help prepare and organise financial information such as financial statements, business income records and tax information that may be required for a mortgage application.
What does an accountant do for a mortgage application?
An accountant can help prepare financial statements, review accounting records, organise income information and provide relevant supporting financial documentation.
Do I need an accountant to apply for a mortgage in NZ?
Not necessarily. However, an accountant may be useful if you are self-employed, operate a business, have multiple income sources or need help preparing financial statements.
Can an accountant help a self-employed person get a mortgage?
An accountant can help a self-employed applicant prepare and organise financial information for a mortgage application. The lender makes the lending decision according to its own requirements.
What financial documents do I need for a mortgage application?
Requirements vary between lenders and applicants. They may include income information, financial statements, tax records, bank records, details of assets and liabilities and other supporting documents.
People Also Ask: Mortgage Application Accountant NZ
Can an accountant help prepare my mortgage application in NZ?
Yes. An accountant can help organise financial statements, income records, tax information and other accounting documents that may be requested by a lender or mortgage adviser.
What does a mortgage application accountant do?
A mortgage application accountant helps prepare and organise the financial information needed to support a mortgage application. This may include financial statements, business accounts, income records and tax information.
Do I need an accountant for a mortgage application in NZ?
Not necessarily. However, an accountant can be useful if you are self-employed, run a business, have multiple income sources or need help preparing financial statements and accounting records.
Can an accountant help self-employed people prepare for a mortgage?
Yes. An accountant can help self-employed applicants organise business income, expenses, financial statements and tax information that may be requested during a mortgage application.
Can an accountant guarantee mortgage approval?
No. An accountant cannot guarantee mortgage approval. The lender makes the final lending decision based on its own criteria and assessment process.
Does DFK Orb360 provide mortgage advice?
No. DFK Orb360 provides accounting, tax and business advisory services and can help clients prepare financial information for a mortgage application. DFK Orb360 does not provide mortgage advice or recommend mortgage products or lenders.
Can an accountant recommend a mortgage lender?
Accounting and mortgage advice are different services. DFK Orb360’s role is to provide accounting and financial information support rather than recommend mortgage products or lenders.
Can an accountant help with mortgage applications for property investors?
Yes. An accountant can help organise relevant business, property and tax records and prepare financial information that may be requested as part of an application.
What is the difference between an accountant and a mortgage adviser?
An accountant helps with accounting, tax and financial records. A mortgage adviser provides financial advice about home loans and lending products.
About This Article
Written by: DFK Orb360 O’Halloran Content Team
Reviewed by: DFK Orb360 O’Halloran Chartered Accounting Team
Published: 22 September 2026
Last reviewed: 22 September 2026
Expertise: New Zealand accounting, taxation, financial reporting, property investment and business advisory
Sources checked: Financial Markets Authority guidance on mortgage advice and financial advice services.
Disclaimer: This article provides general information only and does not constitute mortgage, lending or financial product advice. Mortgage advisers and lenders determine their own requirements, lending criteria and decisions. For regulated mortgage advice, speak with an appropriately authorised financial adviser.

 09 377 4238
 Level 2, 6 Kingdon Street, Newmarket, Auckland
 help@orb360.co.nz